
Here is the number first, because the number is not an opinion.
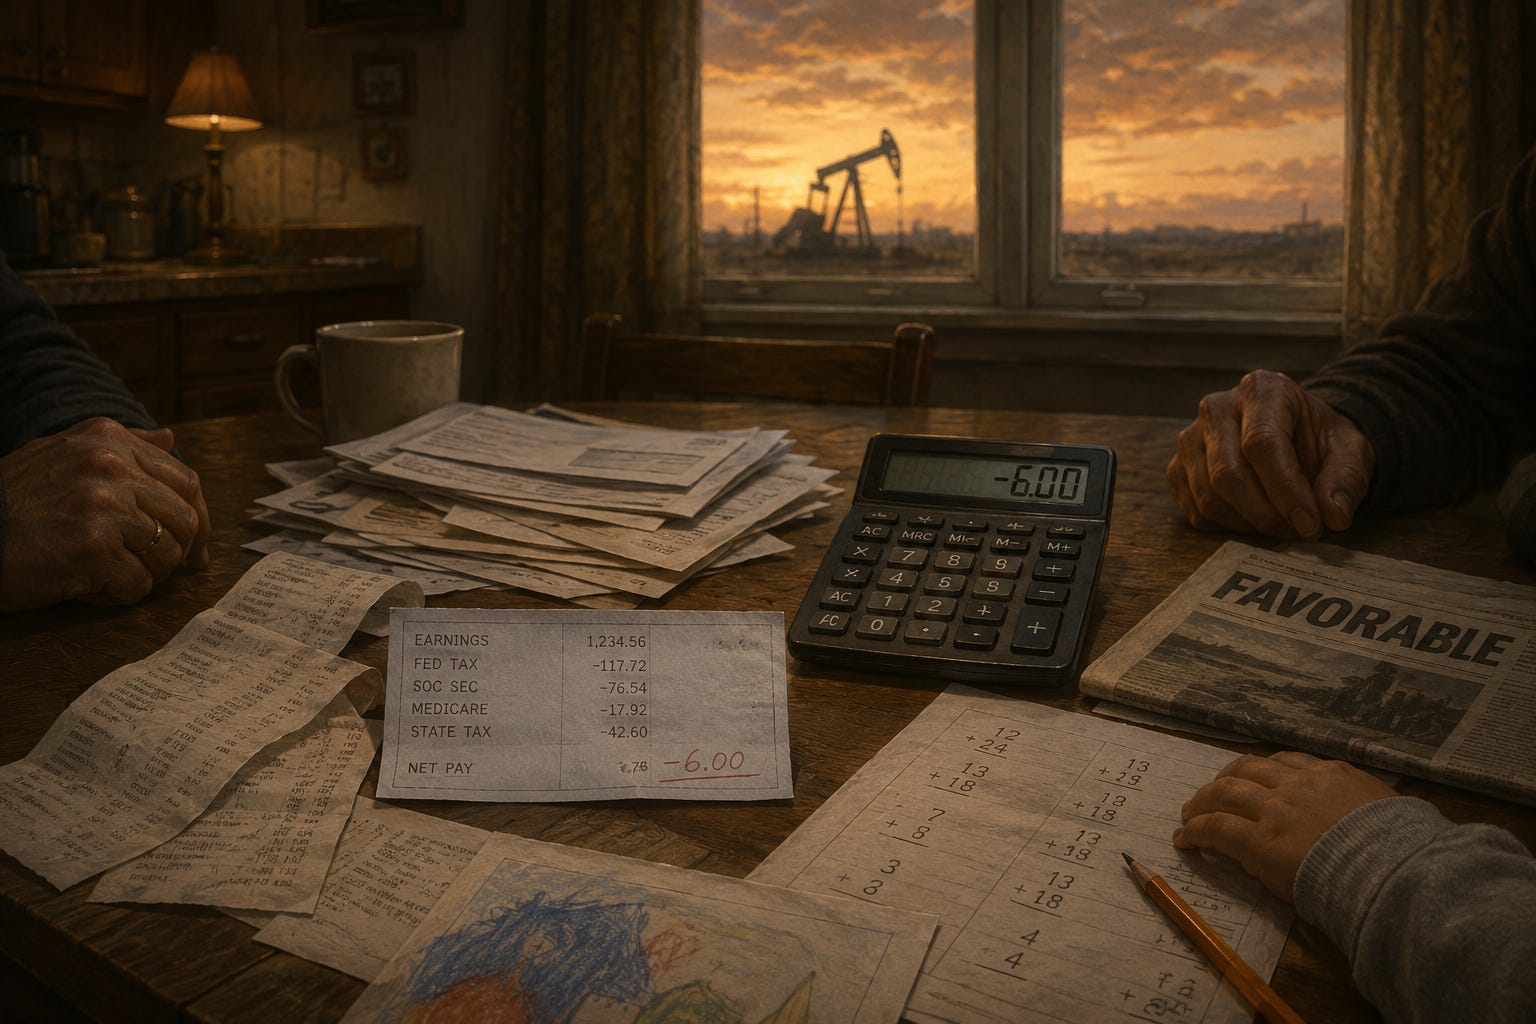
From May 2025 to May 2026, nominal wages in the United States grew 3.7 percent. Inflation over the same period ran 4.2 percent. That half-point gap means the average American took a real pay cut of about six dollars a week, and it is not an isolated month. Wage growth has now trailed inflation in every month since April 2026. Heather Long, chief economist at Navy Federal Credit Union, said it without hedging: "Inflation is now eating up all wage gains for the first time in about three years. This is painful for Americans and a true financial squeeze." Joe Brusuelas, chief economist at RSM, was blunter. Asked about the middle class, the working class, and the working poor, he said their living standards are, right now, in decline.
This is not a projection. This is not a worst-case scenario modeled by an advocacy group with an agenda. This is the Bureau of Labor Statistics, updated as of late June 2026, measuring what has already happened to the paycheck you already earned.
Where the inflation is coming from
Inflation was 2.4 percent in February. It is 4.2 percent now. That is not drift. That is a spike, and the spike has an address: the war with Iran. The conflict disrupted global oil markets and closed the Strait of Hormuz for a period, and even with the war formally ended by a memorandum of understanding in June, the inflationary damage is not undone. Higher oil prices fed directly into headline inflation. Higher fertilizer prices, also driven by the same conflict, are expected to raise food prices further before the year is out, which means the grocery bill has not finished rising. The tariffs layered on top of this, separately from the war, have added their own inflationary pressure, and roughly $165 billion in tariff revenue the government collected has now been found to have been collected illegally and must be repaid, which tells you something about the quality of the policy design that produced the price increases in the first place.
This war was optional. The JCPOA, the deal Trump inherited destroyed and then tried to replace at greater cost, had been functioning before he tore it up in 2018. The war that followed his second-term escalation killed thousands of people, including children, and the bill for that war did not stay in the Middle East. It followed the oil price home and it is sitting in your cart at the grocery store right now, itemized as high fertilizer costs and elevated fuel surcharges, paid by people who never voted for a war and were never asked whether the deal that started it was a good idea.
The housing trap
If wages were merely stagnant, a determined household could still climb by delaying a purchase, waiting out a cycle, renting a little longer. That escape route is closing too. The average 30-year fixed mortgage rate is holding at 6.52 percent as of June 2026. The average US home value is $370,320 and still rising. A middle-class household earning the national middle-income figure of roughly $108,806 is not priced out on paper, but the combination of elevated rates and elevated prices means the monthly payment required to enter homeownership has detached from what a rising-but-inflation-eaten paycheck can service. The ladder is not gone. It has been pulled up two more rungs, and the rungs that remain are wet.
The long arc makes the short-term crisis worse
None of this began in 2025. Real average weekly earnings for the private middle-class wage cohort, a series the Bureau of Labor Statistics has tracked since 1964, currently sit at $1,083, below the $1,140 peak the same cohort reached in the early 1970s. Fifty years of productivity growth, technological transformation, and GDP expansion, and the median worker's inflation-adjusted weekly paycheck is smaller than it was when Nixon was president. The middle-income share of the American population has fallen from 61 percent in 1971 to 51 percent today, hollowed out from both ends: some households climbed, more fell.
This is the fifty-year wound the current administration inherited. What it has done with that wound is reopen it during a period when it had the tools to let it heal. Instead of stabilizing the geopolitical and trade environment enough for wages to catch inflation, which Federal Reserve Chair Jerome Powell explicitly said in December was the precondition for households to start feeling like they were getting ahead, the administration launched a war it did not need to launch, imposed tariffs a court has since ruled were partly illegal, and produced the fastest inflation spike of the past two years at the exact moment the country needed calm.
The official denial
Here is the part that should alarm you most, more than the numbers themselves, because numbers can recover. The United States Treasury Department's own second-quarter 2026 economic policy statement describes the current landscape as "favorable," citing robust business investment and claims that "worker wages continue to outpace inflation, even despite elevated price levels associated with the Iranian conflict."
This is false. The Bureau of Labor Statistics, a separate and independent statistical agency within the same federal government, shows real wage growth of essentially zero in the twelve months through March, turning negative in April and May, worsening every month since. The Treasury Department is not merely spinning a difficult data set. It is asserting the opposite of what its own government's statisticians have measured, in an official policy document distributed to the Treasury Borrowing Advisory Committee, the body that helps determine how the United States finances itself.
A government that cannot accurately describe its own wage data to the body managing its debt is a government that has stopped treating economic reality as a constraint on its messaging. This is not a partisan complaint. It is a structural one. Fiscal policy, monetary policy, and market confidence all depend on accurate data reaching the people who allocate capital. When the Treasury tells the TBAC that wages are outpacing inflation while the BLS says the opposite, someone downstream is making decisions on false premises, and the someone downstream is, eventually, everyone holding a 401k, a mortgage, or a paycheck.
What this administration campaigned against and is now doing
Donald Trump spent the 2024 campaign hammering Joe Biden specifically on the gap between wage growth and inflation, on the "are you better off" question, on the specific grievance that ordinary Americans were falling behind while official statistics claimed the economy was strong. That was, for a period under Biden, a legitimate criticism grounded in real data. The current administration is now presiding over the identical condition it built its campaign on opposing, at a worse rate of divergence, driven substantially by a war of its own choosing, and its official response is to publish a Treasury statement claiming the problem does not exist.
There is no version of this that is not dismal, and dishonesty about it does not make it less dismal. It makes it more dangerous, because a household that believes the official story will not adjust in time, will not renegotiate, will not push for the raise or take the second job or delay the purchase, because the government told them things were favorable. The lie has a cost, and the cost falls hardest on the people least equipped to absorb a surprise.
Where this goes
Deloitte's forecast has wage growth continuing to moderate through the rest of 2026, private sector hourly earnings already down to 3.4 percent in May from roughly 4 percent in 2024 and 2025, with no acceleration expected given muted labor demand and a working-age population that is barely growing due to immigration enforcement reducing the labor pool that would otherwise support wage-side growth. The Fed may be forced to raise rates before the year is out specifically because of the war-driven inflation, which would further slow hiring and further compress the middle class from the employment side while the price side continues to bite from the war and tariff exposure already locked in.
Economists surveyed by CBS News flagged affordability as the central question of the 2026 midterms before any of this year's inflation spike had even occurred. It is now the central question with sharper teeth, because the spike is real, it is measured, it is ongoing, and it is layered on top of a fifty-year erosion that had already left the median household with less purchasing power than their grandparents had in 1972.
The middle class did not imagine this. It is in the BLS data, updated weekly, independent of anyone's spin. The war is in the grocery bill. The mortgage rate is in the housing trap. The tariffs were partly illegal and still cost money. And the government's own finance ministry is telling the people who buy its debt that everything is favorable, while the people who work for a living watch their paychecks buy six dollars less every week than they did a year ago.
That is not a talking point. That is the arithmetic. The arithmetic does not care who is in the Situation Room.